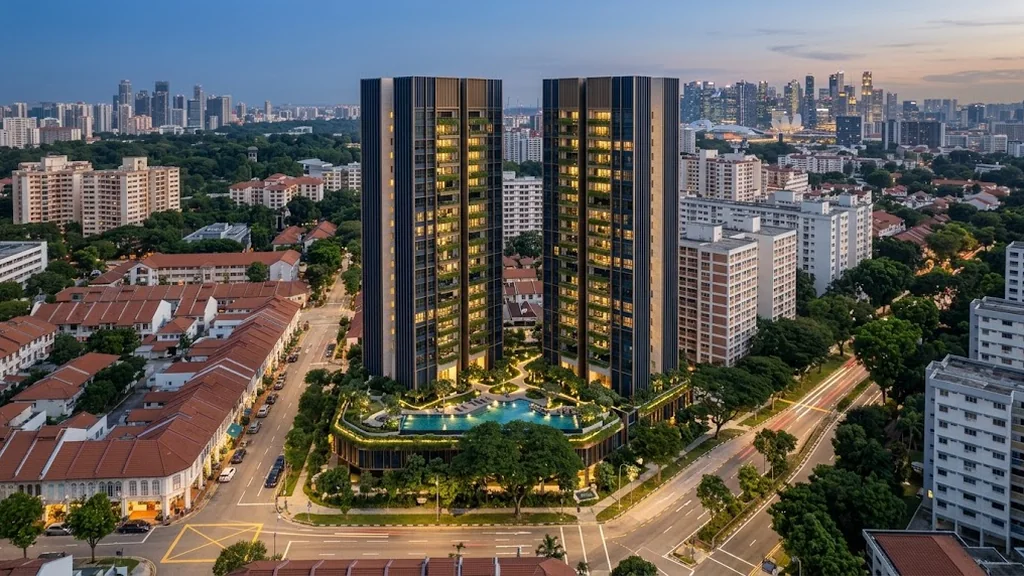
This Dorset Gardens TDSR calculator estimates the maximum housing loan the applicant's income can support under the Monetary Authority of Singapore's Total Debt Servicing Ratio framework, then compares it against the Loan-to-Value ceiling so the binding limit is clear. Dorset Gardens is private residential property, so the private-property rules apply. The full framework is set out on the housing loan page.
Main Applicant
MAS applies a 30% haircut.
Car, personal and other property loans.
Joint Applicant
MAS applies a 30% haircut.
Car, personal and other property loans.
Maximum 35 years for private property.
Rates below 4% are assessed at the 4% floor.
Sets the Loan-to-Value ceiling.
Indicative only. MAS moves the loan to its lower LTV tier — 55%, 25% or 15% for no, one, or two or more housing loans outstanding — when the tenure tops 30 years or the loan would still be running after age 65 (taken on the income-weighted average age for joint borrowers); a first-loan buyer in that tier pays at least 10% of the price in cash rather than 5%. Where the LTV limit is below the TDSR limit, the property loan is the binding constraint. Banks apply their own credit policies — confirm with a bank, or ask the appointed marketing team to arrange an In-Principle Approval. Do not include an existing home loan that will be discharged before this purchase.
How the Dorset Gardens Loan Maths Works
Banks first compute assessed income — fixed income in full, variable income (bonuses, commissions, rental) averaged monthly and cut by 30%. The TDSR ceiling is 55% of that figure across all monthly debts, and the headroom left after existing obligations is converted to a loan quantum over the selected tenure at the assessment rate, with MAS’s 4% floor applied whenever a lower rate is entered. Joint borrowers are tested on the income-weighted average age: a loan still running after 65 on that age, or longer than 30 years, takes the lower loan-to-value tier, which is why the younger, higher-earning borrower carrying more of the income can keep a long loan at the full ceiling.
The result is then capped by the Loan-to-Value ceiling on the purchase price: 75% for a first housing loan, 45% with one loan outstanding, 35% with two or more, or 55%, 25% and 15% in the lower tier. Whichever of the two limits — income (TDSR) or property (LTV) — is lower is the one that binds. Stack this with the stamp duty calculator and the progressive payment calculator for the complete picture, then book a showflat visit.
Register for Dorset Gardens Updates
Once you know your budget, the next step is the price list. Registered parties receive it first.